Showing posts with label Spain. Show all posts

Friday, June 29, 2012

Eurozone bank bailout deal throws lifeline to Spain and Italy

Italy and Spain stunned Germany by blocking progress until they obtained softer bailout rules in 14 hours of bad-tempered talks
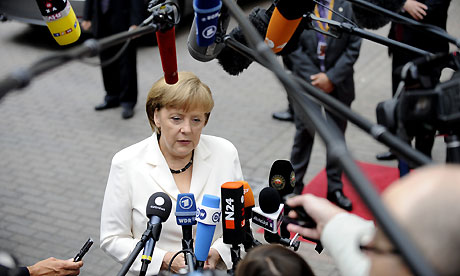


German chancellor Angela Merkel
German chancellor Angela Merkel arrives for day two of the summit in Brussels on Friday. Photograph: John Thys/AFP/Getty Images


European leaders have pulled back from the brink of disastrous failure in their attempts to rescue the euro, throwing a lifeline to the weakest links in the eurozone by agreeing to shore up struggling banks directly, remove disadvantages for private creditors and move quickly towards a new supervisory regime for banks.

David Cameron said on Friday: "The countries of the eurozone did take some important steps forward last night. There's still important work to do."

Amid bad-tempered talks that continued through the night, Italy andSpain stunned the Germans by blocking progress on an overall deal at a two-day EU summit in Brussels until they obtained guarantees that the eurozone would act to cut the soaring costs of their borrowing.

The tough negotiations were deadlocked for hours, prompting the departure from the summit after midnight of the 10 non-euro countries, including Britain, leaving the eurozone leaders to fight it out.

Tuesday, June 26, 2012

Spain and Italy suffer new economic setbacks


Borrowing costs jump and stock markets fall as investors seek safer havens


  • Spanish bank


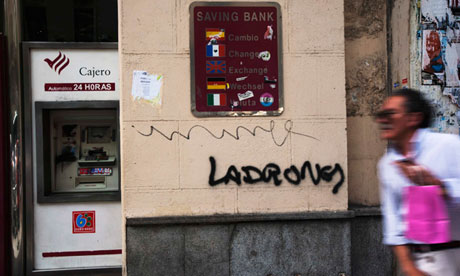
A man walks past graffiti on the wall of savings bank Cajastur in Madrid on 26 June. Photograph: Susana Vera/Reuters


Spain and Italy were mired in financial woes again on Tuesday after borrowing costs jumped, stock markets fell and local politicians warred with each other over who is to blame for the financial crisis.

Spanish borrowing costs jumped following the government's application for a €100bn eurozone rescue facility to prevent the country's banks going bust.

The interest rate on a batch of three- and six-month bonds almost doubled as the precarious situation of Spain's banking sector and the knock-on effects for government finances sent most investors scurrying for safer havens.

A lack of agreement in Brussels during the day also panicked bond investors, many of which have lent billions of euros to crisis-hit countries, raising the cost of long-term borrowing. Reported comments by Angela Merkel that Europe would not have pooled debt liability "as long as I live" added to investor concern.

Bond auctions have become a litmus test of a country's viability and rebuilding the faith of private investors lies at the heart of discussions between European leaders. While the focus has been on Spain and Italy and the countries in receipt of direct EU funds – Ireland, Portugal and Greece – France is also under the spotlight. After a brief honeymoon following the election of President François Hollande last month, French interest rates have begun to rise.

Monday, June 25, 2012

Spain requests EU aid, market hopes dim

A cleaner cleans the facade of a Bankia-Caja Madrid bank branch in the Andalusian capital of Seville June 25, 2012. Spain formally requested European aid for its banks on Monday but did not specify how much money it will seek to recapitalize the indebted lenders. REUTERS-Marcelo del Pozo


MADRID/BRUSSELS | Mon Jun 25, 2012 9:44am EDT


(Reuters) - Spain formally requested euro zone rescue loans on Monday to recapitalize banks that are laden with bad debts as the euro and shares fell due to investors' skepticism that a European Union summit this week will act decisively on the bloc's debt crisis.

Spanish Economy Minister Luis de Guindos asked for up to 100 billion euros ($125 billion) in a letter to Euro group chairman Jean-Claude Juncker, saying the final amount of assistance would be set at a later stage.

He confirmed his intention to sign a Memorandum of Understanding for the package by July 9 and said the amount should be enough to cover all banks' needs, plus an additional security buffer.

The EU's top economic official, Olli Rehn, said a deal on terms for the loan from Europe's bailout funds could be concluded in a matter of weeks.

"The policy conditionality of the financial assistance, in the form of an EFSF/ESM loan, will be focused on specific reforms targeting the financial sector, including restructuring plans which must fully comply with EU state aid rules," he said.

Sunday, June 24, 2012

Banks downgraded as size of Spanish crisis revealed


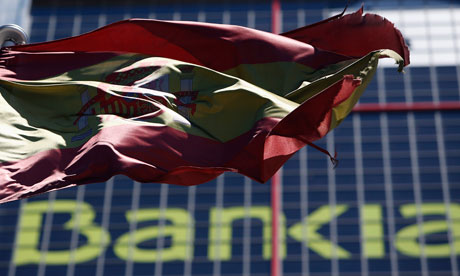
A Spanish flag flutters in front of the headquarters of Bankia
Bankia, Spain’s fourth biggest lender, has already been forced to seek government support in the Spanish banking crisis. Photograph: Sergio Perez/Reuters


Moody's has cut the ratings of 15 of the world's biggest banks, hours after the markets were digesting the admission by Spain that its banks could need up to €62bn of bailout money to see them through the next three years.

The result of the independent audit of Spain's banks put the gap in their finances at between €16bn and €62bn – similar to the €50bn calculated by the International Monetary Fund (IMF) two weeks ago.

Banking giants including Bank of America, Barclays, Citigroup, HSBC, Goldman Sachs, Morgan Stanley and Royal Bank of Scotland all had their credit ratings cut.

The ratings agency said the cuts reflected declining profitability
in an industry suffering from a slowdown in economic growth, tougher
regulations and nervous investors.